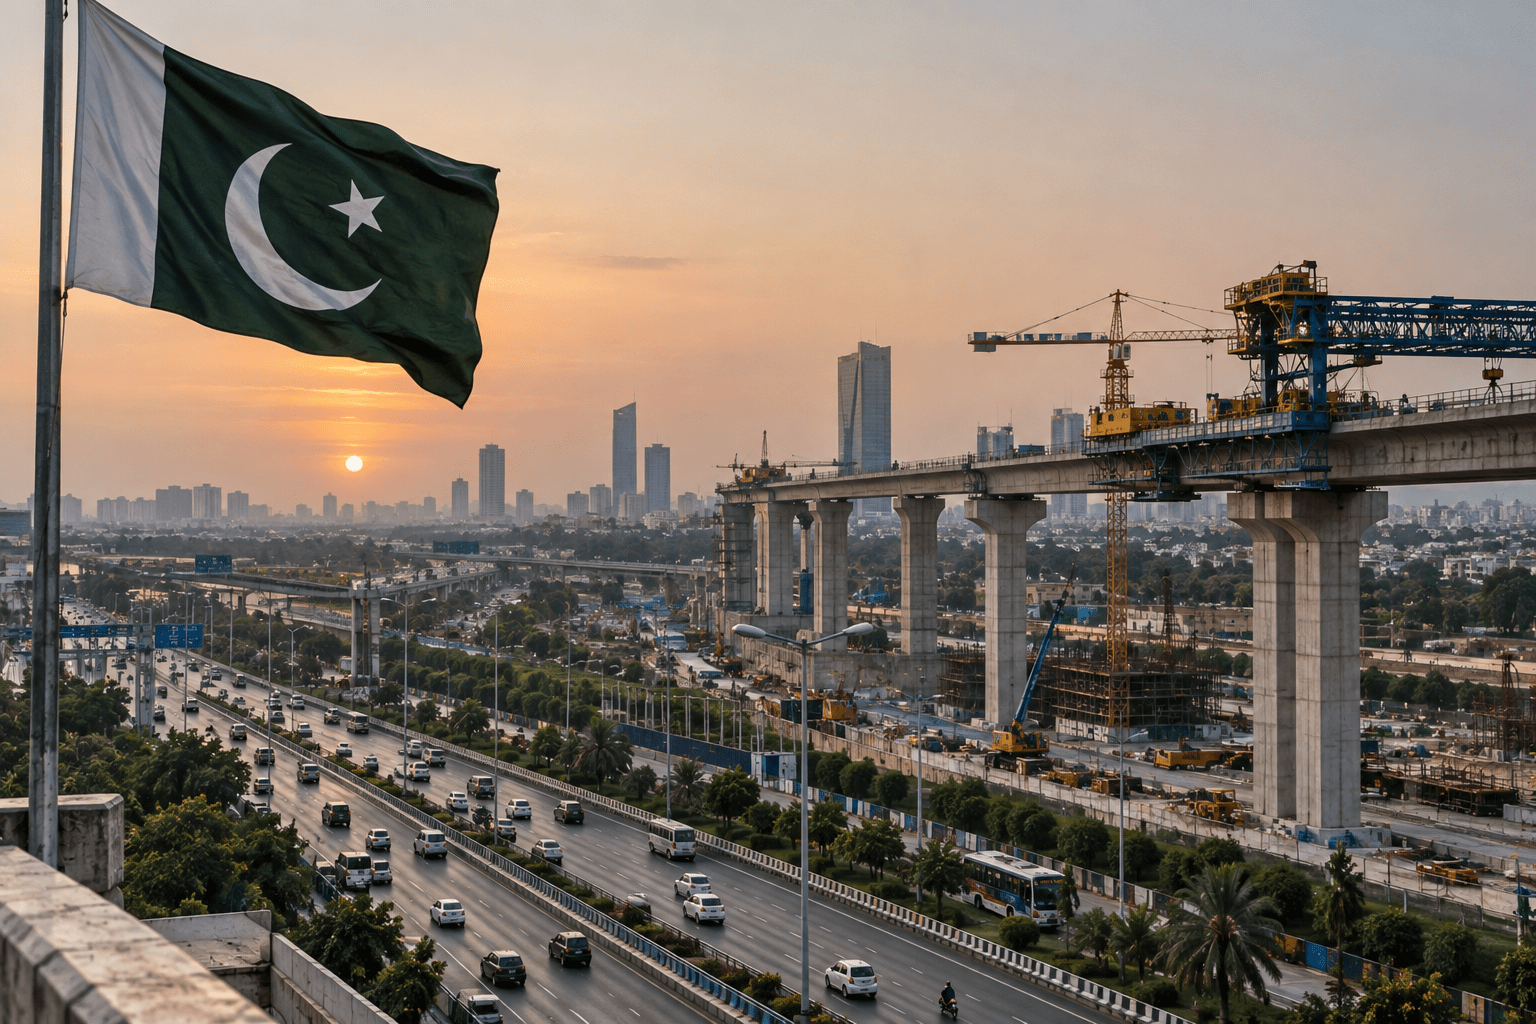
Pakistan is preparing 38 PPP projects worth around $6.5 billion. Here's what the pipeline means for infrastructure, investors and private-sector growth.
By Boardroom Research Desk
Pakistan Needs Private Capital. But Private Capital Needs Bankable Projects.
Pakistan has a financing problem.
But increasingly, it also has an infrastructure-financing opportunity.
The government has identified 38 federal projects worth around $6.5 billion for potential public-private partnership financing.
The pipeline covers roads, railways, aviation, healthcare and industrial infrastructure.
At the same time, the government is advancing the privatization of 27 state-owned assets.
This represents a potentially important change in how Pakistan thinks about infrastructure.
Instead of asking:
How much can the government spend?
The more relevant question becomes:
How much private capital can Pakistan mobilize around properly structured public assets and projects?
Pakistan Already Has Experience
PPP is not new to Pakistan.
According to the Pakistan PPP Monitor, the country has completed 154 PPP transactions involving almost $36 billion of investment since the 1990s.
The new pipeline therefore does not represent the beginning of PPPs.
It represents an attempt to make private capital a much more important part of future infrastructure financing.
That distinction matters.
Pakistan is not testing whether PPPs are possible.
It is testing whether they can become scalable.
Why the Model Makes Sense
Government budgets are finite.
Infrastructure requirements are not.
Pakistan needs better transport networks, energy infrastructure, logistics, healthcare facilities, urban services and industrial infrastructure.
At the same time, fiscal constraints limit how quickly the public sector can finance all of these requirements.
Private capital can potentially bridge part of that gap.
But the private sector does not invest because a project is socially desirable.
It invests when a project is:
Bankable
Transparent
Properly structured
Predictable
and offers an appropriate risk-adjusted return.
That is where Pakistan's real challenge begins.
A PPP Is Not Free Money
There is a tendency to describe PPPs as if they remove the government's financial burden.
They do not.
A well-structured PPP can distribute financing, construction, operational and demand risks between public and private parties.
But governments may still have to provide guarantees, availability payments, land, regulatory support or other forms of commitment.
That means PPPs should not be judged by how much government spending they appear to avoid.
They should be judged by whether they deliver better infrastructure and better value for money.
Project Preparation Is Everything
Investors can tolerate commercial risk.
They struggle with uncertainty.
A project with unclear land ownership is difficult to finance.
A project with unpredictable tariffs is difficult to finance.
A project with uncertain government obligations is difficult to finance.
A project without reliable demand data is difficult to finance.
Therefore, Pakistan's PPP agenda should place enormous emphasis on project preparation before projects are presented to investors.
This is an analytical recommendation, not a reported government commitment.
But it is arguably the difference between a pipeline and a transaction.
The Privatization Link Matters
The government's parallel effort to privatize 27 state-owned assets creates another potential channel for private capital.
The assets reportedly include power distribution companies, major airports, insurance companies and specialized banks.
Again, the headline number is less important than execution.
Privatization should not simply mean transferring ownership.
The broader objective should be to introduce:
Better management
Capital investment
Operational efficiency
Technology
Governance
and where appropriate, greater competition.
Pakistan's Investors Need Long-Term Opportunities
There is another important dimension.
Domestic institutional investors need investable assets.
Banks, pension funds, insurance companies, asset managers and other institutions need opportunities that match long-term liabilities and investment objectives.
A mature PPP ecosystem can potentially create such opportunities.
Infrastructure assets are naturally long-term.
That makes them potentially suitable for long-duration capital, provided the regulatory and contractual framework is robust.
The $6.5 Billion Is a Starting Point
It would be premature to describe the $6.5 billion pipeline as $6.5 billion of committed investment.
It is a pipeline, not completed financing.
That distinction should remain clear.
The value of the announcement will ultimately depend on how many projects reach financial close, how many are delivered on time and whether the resulting infrastructure improves economic productivity.
Boardroom View
Pakistan cannot finance its infrastructure ambitions through government expenditure alone.
Private capital will have to play a larger role.
But the country should not measure success by the number of projects announced.
It should measure success by the number of bankable projects financed, completed and operating effectively.
The opportunity is substantial.
Pakistan has capital.
Pakistan has infrastructure needs.
The missing link is often the structure that brings the two together.
The next stage of Pakistan's PPP story should therefore be about execution, not announcements.